Property tax is the bill that can make a dream home feel more expensive than expected. A listing price may look fair, the mortgage may fit the budget, and the neighborhood may feel right.
Then the yearly tax bill arrives, and the real cost of owning that home becomes much clearer.
That is why so many buyers ask: Are there any states with no property tax? While every state has some form of property tax, not every homeowner pays the same kind of bill.
Some states keep property taxes low enough to make a big difference over time.
This guide helps you see which states have the lowest property taxes, how much the gap can affect your wallet, and what to check before choosing where to buy, move, or settle next.
Are There Any States with No Property Tax?
No state in the United States has eliminated property tax.
Despite common claims online, every state allows local governments to collect property taxes to fund public services such as schools, roads, emergency response, and local infrastructure.
However, some states do not impose a separate state-level property tax and instead leave taxation entirely to counties, municipalities, or other local authorities.
Alaska and Hawaii are examples of this structure. Property taxes are still collected, but rates are determined at the local level.
The results differ significantly. Alaska’s effective property tax rate is about 0.98%, while Hawaii has the lowest effective rate in the country at roughly 0.27%.
Although property taxes cannot be avoided completely, choosing a low-tax state can reduce annual housing costs by thousands of dollars.
Before settling on a state, it also helps to understand the rules for joint property ownership, since how a deed is titled affects both tax liability and what happens to the property later.
10 States With the Lowest Property Tax Rates
The following states have the lowest effective property tax rates based on 2026 Tax Foundation and American Community Survey data, with effective rates showing the actual share of home value paid each year.
No. State Effective Rate Annual Tax on $300K Home Annual Tax on a $500K Home 1 Hawaii 0.27% $810 $1,350 2 Alabama 0.38% $1,140 $1,900 3 Idaho 0.43% $1,290 $2,150 4 Tennessee 0.45% $1,350 $2,250 5 Nevada 0.47% $1,410 $2,350 6 Colorado 0.49% $1,470 $2,450 7 Louisiana 0.55% $1,650 $2,750 8 Delaware 0.57% $1,710 $2,850 9 South Carolina 0.57% $1,710 $2,850 10 West Virginia 0.58% $1,740 $2,900 The main takeaway is simple: a low effective rate can make the same-priced home far cheaper to own year after year.
Why Low Property Tax Rates Can Still Mean High Bills
A low property tax rate does not always mean a low yearly bill. Hawaii has the lowest effective rate at 0.27%, but high home values push the median annual tax bill to about $2,385.
Alabama shows the opposite case. Its 0.38% rate, combined with lower home values, brings the median bill to about $890 per year.
The smallest actual property tax bills usually appear where both rates and home values stay low:
- West Virginia: Median annual bill around $835 due to modest home values and a low rate.
- Alabama: Median annual bill around $890, with some counties charging even lower rates.
- Louisiana: Median annual bill around $897 in many parishes, helped by homestead exemptions.
For buyers comparing total housing cost, the dollar amount matters more than the rate alone.
Best Low Property Tax States by Homeowner Type
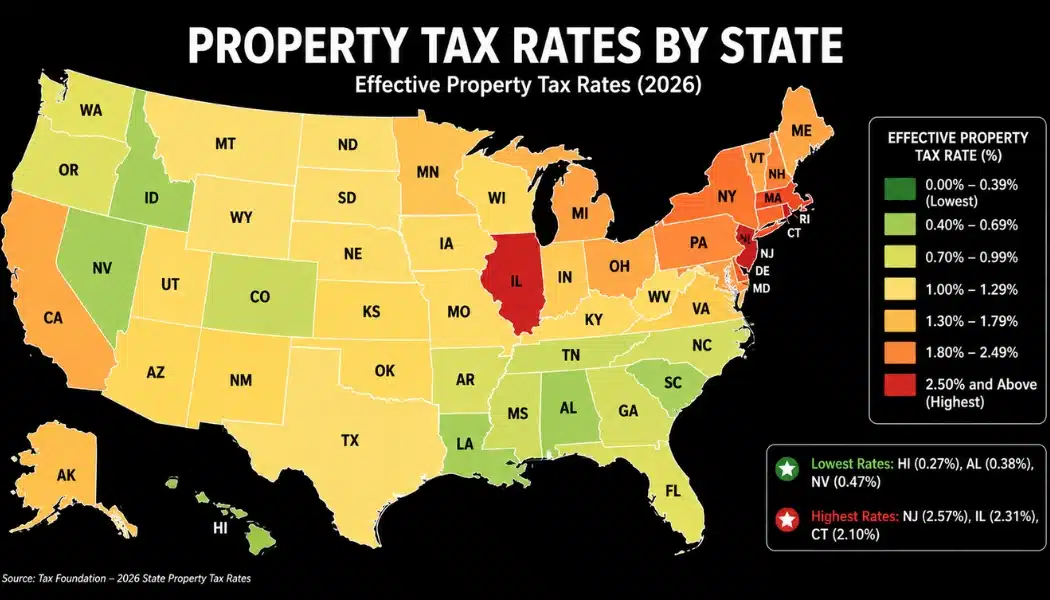
Choosing a low-property-tax state depends on more than the rate alone, since home prices, exemptions, income taxes, school needs, and long-term protections all shape the real cost of ownership.
Based on those factors, different states may fit different homeowner profiles.
1. Best Low Property Tax States for Retirees
Retirees often benefit from states that combine low property taxes, no state income tax, and senior relief options.
Tennessee, Alabama, and Nevada are strong choices for fixed-income homeowners. Tennessee has a 0.45% effective property tax rate and no state income tax.
Alabama offers affordable housing and one of the lowest median tax bills. Nevada adds value through tax caps that help limit large increases in the value of primary residences.
2. Best Low Property Tax States for Families
Families usually need to compare property taxes with school access, housing costs, and neighborhood stability.
Idaho, South Carolina, and Colorado may be good options for families seeking a lower tax burden without ignoring education needs.
Idaho has a 0.43% effective rate, while South Carolina and Colorado maintain moderate rates compared with many high-tax states. Local school quality still varies, so county and district research matters.
3. Best Low Property Tax States for First-Time Homebuyers
First-time homebuyers often need lower purchase prices and manageable yearly tax bills.
Alabama, West Virginia, and Louisiana stand out because they combine modest home values with low effective property tax rates.
Alabama is especially attractive for budget-focused buyers, with many areas below 0.40% and median annual bills under $900. These lower carrying costs can make homeownership easier to maintain after closing.
4. Best Low Property Tax States for Long-Term Homeowners
Long-term homeowners benefit most from low rates, homestead protections, and rules that limit sharp increases over time.
Hawaii, Nevada, and Delaware are strong options for owners planning to stay for many years.
Hawaii has the lowest effective rate at 0.27%, while Nevada offers a tax cap on primary residences. Delaware also keeps property taxes low, helping long-term owners control annual housing costs.
Note: All property tax rates and comparisons in this post are drawn from the latest available data. For complete details and county-level breakdowns, visit: Tax Foundation’s 2026 data
Why Property Taxes Vary So Much by State
Property taxes vary widely by state because local governments control how homes are assessed, taxed, and exempted.
- Local Control: Property taxes are set mostly by state and local governments, not federal law, which creates major differences in rates, rules, exemptions, and relief programs.
- School Funding Dependence: Areas that rely heavily on property taxes to fund public schools and local services often have higher effective tax rates.
- Assessment Methods: Some states tax homes based on full market value, while others use replacement cost, assessed value, or fractional assessments.
- Exemptions and Tax Caps: Homestead exemptions, senior relief, veteran exemptions, and assessment caps can lower taxable value and reduce effective rates in states such as Nevada, Hawaii, and Louisiana.
- Home Values: High-value states may have low tax rates but still produce large bills because home prices are higher.
- Economic and Revenue Mix: States that rely more on sales taxes, tourism revenue, income taxes, or other sources may keep property tax rates lower.
- Historical Policy Choices: Voter-approved limits, long-standing tax caps, and state budget decisions shape property tax burdens from one state to the next.
Regional Breakdown of the Lowest Property Tax States

Low-property-tax states are not evenly distributed across the country.
Regional patterns matter because home values, local funding systems, exemptions, and state tax policies all affect the final bill.
1. Southern States With the Lowest Overall Property Tax Burden
The South generally offers the lowest overall property tax burden. Alabama, Louisiana, South Carolina, Tennessee, and West Virginia all combine low effective rates with modest home values.
That mix often creates smaller annual bills than buyers find in higher-cost regions.
Homestead exemptions and lower housing prices also make several Southern states attractive for homeowners focused on long-term affordability.
2. Western States With Low Rates but Higher Home Prices
The West has several low-rate states, including Hawaii, Idaho, Nevada, and Colorado. These states rank well for effective property tax rates, but home prices can affect the final bill.
Hawaii has the lowest rate nationally, yet high home values can still produce sizable tax payments.
Colorado shows the same issue in some expensive local markets. Buyers should compare rates and prices before deciding where.
3. Northeast vs South: Where Property Taxes Differ Most
The sharpest property tax gap appears between the Northeast and the South. New Jersey, New York, and Connecticut often carry much higher tax burdens than Southern states.
On the same home value, the annual bill can differ by thousands of dollars.
For buyers comparing regions, this gap can become one of the biggest long-term ownership costs over a full mortgage period.
Property Tax Exemptions That Can Lower Your Bill
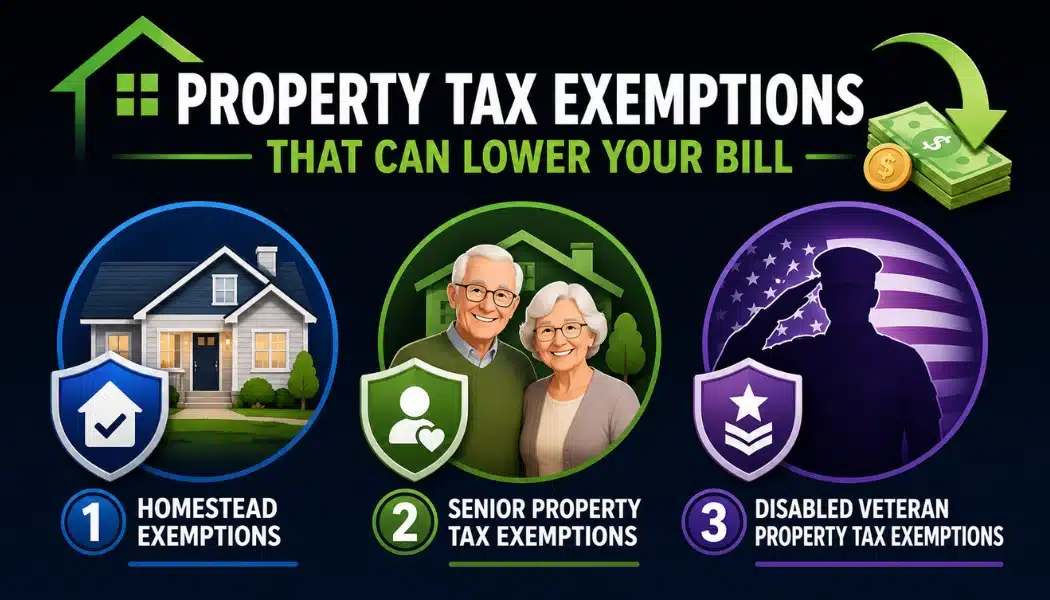
Even in higher-tax states, exemptions can lower a homeowner’s yearly bill if they qualify based on residence type, age, disability status, or income, with savings varying by state law and local assessment rules.
- Homestead Exemptions: Homestead exemptions lower the taxable value of a primary residence, reducing the amount used to calculate property taxes each year.
- Senior Property Tax Exemptions: Senior exemptions help older homeowners reduce, freeze, or offset property tax increases. Most programs begin around age 62 or 65 and often include income limits.
- Disabled Veteran Property Tax Exemptions: Disabled veteran exemptions can reduce or fully remove property taxes for qualifying homeowners, with the strongest programs often applying to veterans with a 100% permanent and total VA disability rating.
Homeowners who qualify for these programs may also want to consider broader strategies to protect their homes and assets from financial and legal exposure.
High Property Tax States to Compare Carefully
For buyers weighing where to purchase, the high-rate end of the spectrum is worth knowing.
Current 2026 data from the Tax Foundation and American Community Survey place these states at the top of the effective rate rankings.
Note that exact figures vary by source and methodology; the ranges below reflect data seen across multiple current sources.
State Effective rate (approx.) Notes New Jersey 2.14%–2.42% Consistently the highest in the country. Median annual bill exceeds $9,000 in many counties. Illinois ~2.08% Some Cook County districts reach 2.50%+. Over 6,900 local taxing districts statewide. Connecticut 1.98%–2.15% 169 towns each fund their own services independently, driving up rates. New Hampshire ~2.05% No state income tax; relies heavily on property taxes instead. New York 1.70%+ (varies widely by county) New York City has unique abatement programs; upstate counties are among the highest nationally. Over a 30-year mortgage on a $400,000 home, the difference between New Jersey’s top rates and Hawaii’s 0.27% rate can exceed $230,000 in total property taxes paid.
Could Any State Eliminate Property Tax?
Several states have debated capping or eliminating property taxes in recent legislative sessions, but no state has come close to full elimination as of 2026.
The primary obstacle is revenue: property taxes fund K-12 education and local services in most states, and replacing that revenue requires either raising other taxes or cutting services significantly.
States that have explored significant property tax reform recently include Texas (which has passed partial relief measures), Montana, and Wyoming.
These efforts typically focus on expanding homestead exemptions or capping assessment increases rather than outright elimination.
Full elimination remains politically and fiscally difficult.
States that already rely less on property tax (because they use income tax or sales tax revenue instead) are the most likely candidates for future reduction, but none have announced a credible elimination timeline.
If you are researching this topic for a relocation decision, verify current legislative status directly with the state’s Department of Revenue or a local tax professional.
What to Do If Your Property Tax Assessment Seems Wrong
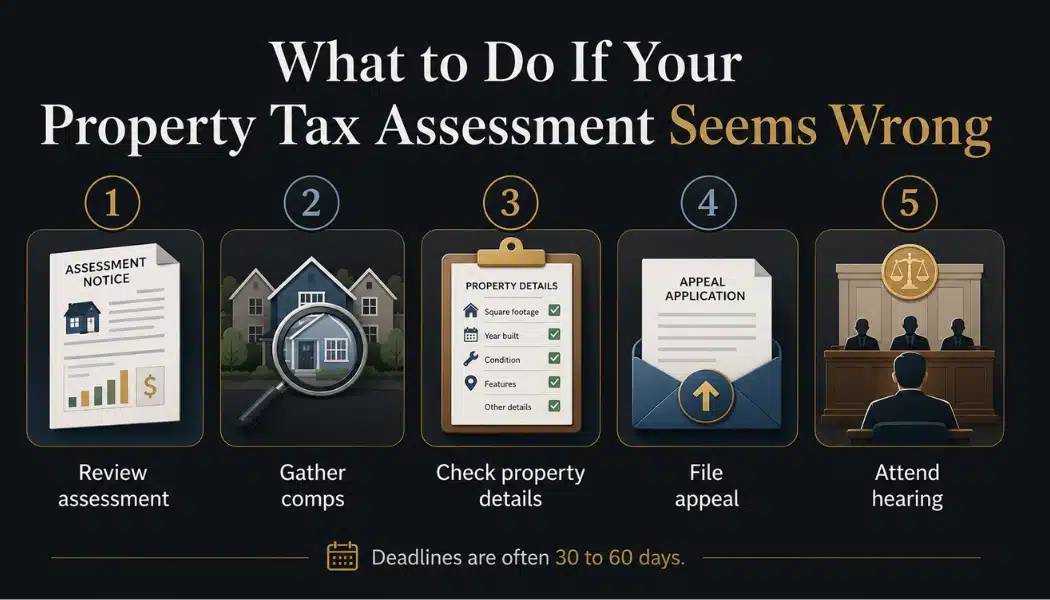
Homeowners can appeal a property tax assessment when the assessed value appears higher than the home’s fair market value.
A successful appeal may lower the taxable value and reduce the yearly bill.
The usual steps include:
- Review the assessed value listed on the notice from the county assessor.
- Collect evidence, including recent comparable sales of similar homes nearby.
- Check details such as square footage, condition, lot size, location, and sale date.
- File the appeal with the county assessor, board of equalization, or local review office before the deadline.
- Present the evidence at a hearing if required.
Deadlines are often short, usually 30 to 60 days after the notice is mailed. This is general information only, not legal or financial advice. Always confirm rules with the local assessor’s office.
Conclusion
No state completely removes property tax, but the amount homeowners pay can vary widely.
The smartest move is to compare effective rates, home values, exemptions, and assessment rules before choosing where to buy or settle.
A low rate can reduce yearly costs, while a high rate can add thousands over time. Property tax is not just a local bill. It is part of the real cost of homeownership.
Before making a decision, review the numbers carefully, confirm current rules with local tax offices, and speak with a qualified professional when legal or financial questions arise.
The right information can help homeowners avoid costly surprises and make a more confident property decision.
Have questions about property taxes in your state or experience with unexpected tax costs? Share your thoughts in the comments below.
Note: This blog provides general informational context only and does not constitute financial or legal advice. Consult a qualified tax professional or attorney before making any relocation or real estate decision.
Frequently Asked Questions
Do Property Taxes Go Away After a Mortgage Is Paid Off?
No. Property taxes continue as long as you own the home. After payoff, you may need to pay the tax bill directly instead of through escrow.
Do Renters Pay Property Taxes?
Not directly. Landlords pay the property tax bill, but the cost is often built into rent.
Can Buying Land Instead of a House Help Avoid Property Taxes
No. Vacant land is still taxable, though taxes may be lower than on land with a house or major structure.