Most people assume Medicaid covers an aging parent’s care when they can no longer pay for it themselves. In most cases, that’s true, but there’s a little-known legal twist that can surprise families with unexpected bills.
In nearly half of the U.S., filial responsibility laws allow care providers to seek payment from adult children for a parent’s unpaid living or medical expenses.
While these laws are rarely enforced, they remain in effect in many filial law states, and enforcement can occur under the right circumstances.
If you have aging parents, understanding which states with filial responsibility laws still recognize these statutes and when they can be applied could help you avoid costly surprises.
This guide explains where these laws exist, how they work, and what legal risks adult children may actually face.
What are Filial Responsibility Laws?
Filial responsibility laws are state statutes that can require adult children to provide financial support to parents who cannot support themselves.
The term filial comes from the Latin word for sons and daughters.
These laws date back to colonial-era poor laws and were designed to prevent indigent individuals from becoming a public burden. Although many states still have them, they are rarely enforced.
In certain cases, nursing homes, care facilities, or government agencies may seek payment from financially able adult children when an indigent parent cannot cover essential expenses such as housing, food, or medical care.
The greatest risk often occurs during gaps in Medicaid coverage. For example, a parent may enter a nursing facility before Medicaid approval is finalized, leaving unpaid bills that providers may attempt to recover from adult children.
States With Filial Responsibility Laws
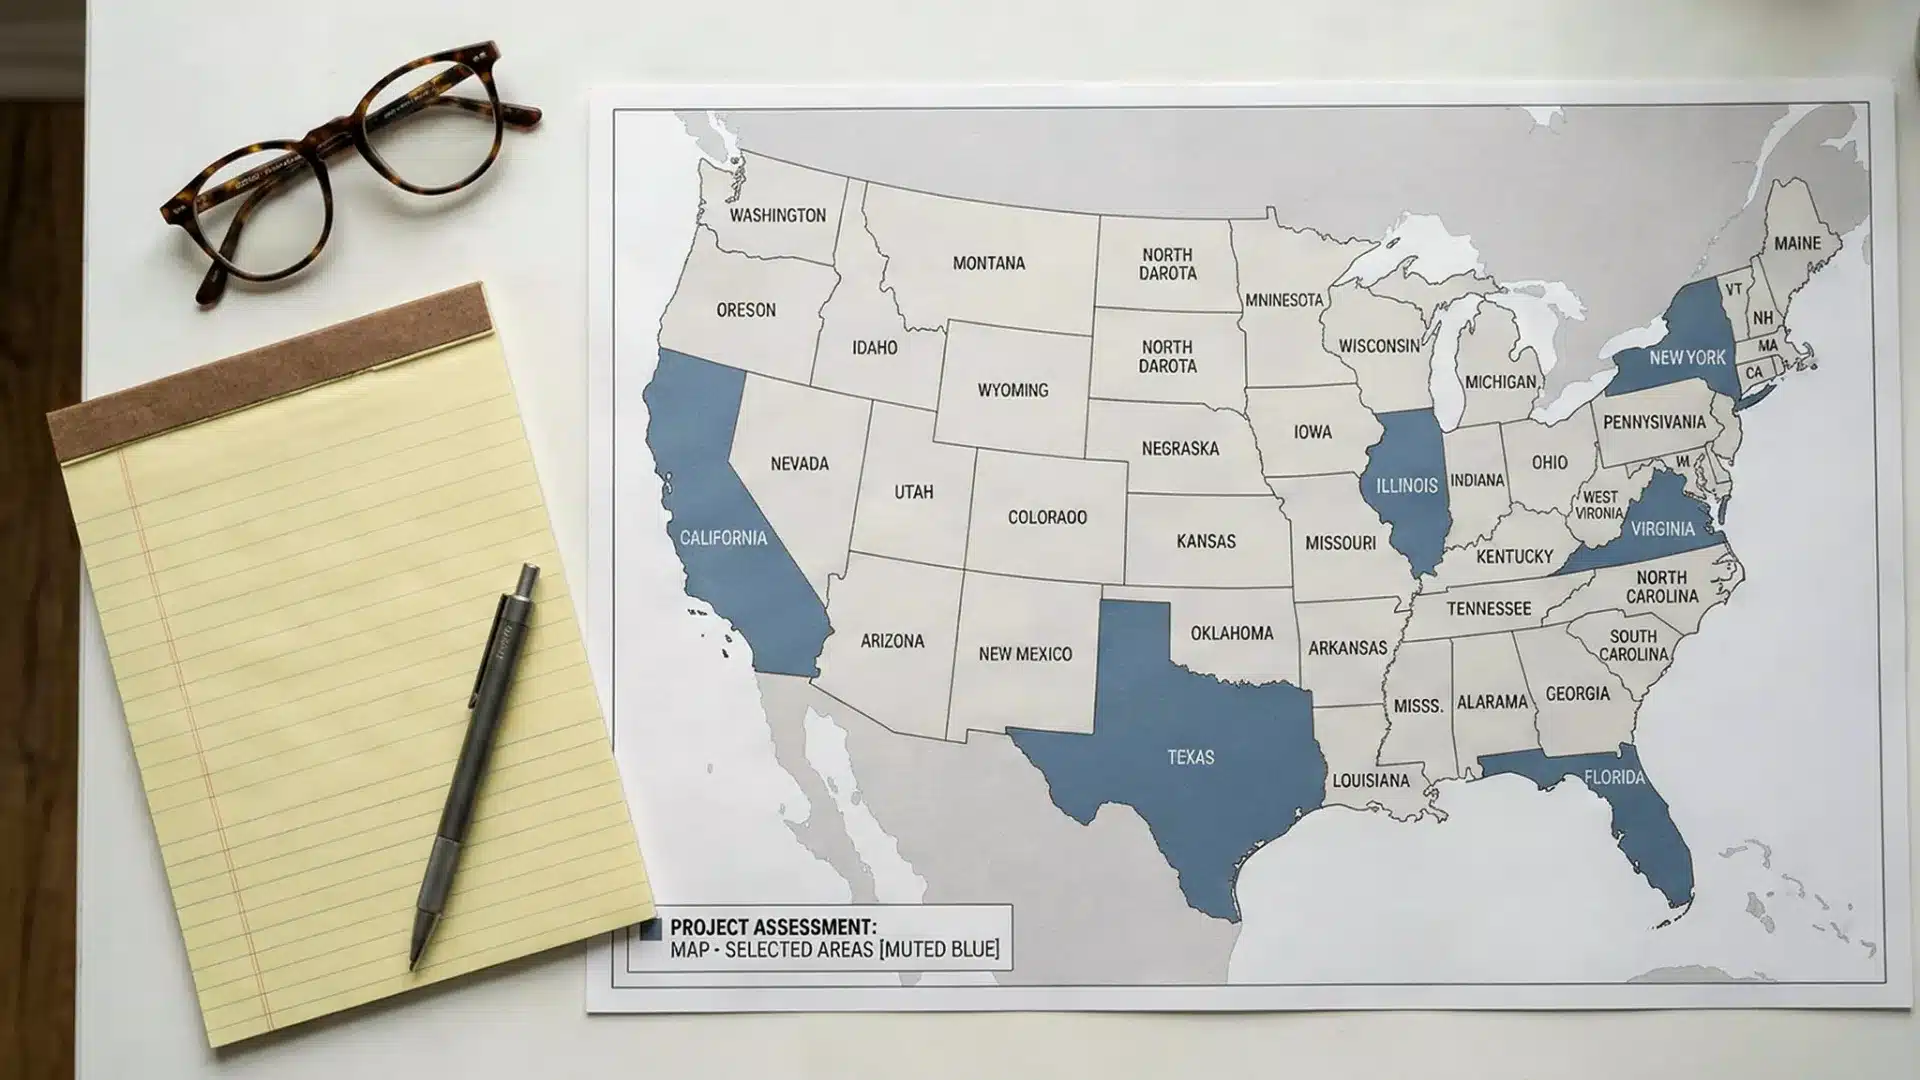
The number of states with filial laws fluctuates as legislatures act, but current tracking from the National Conference of State Legislatures (NCSL) places the figure at approximately 27 to 28 states.
The following states have some form of a filial responsibility statute on the books.
| State | Key notes |
|---|---|
| Alaska | Two-way duty; parents and children must support each other when the other is unable to work |
| Arkansas | Limited scope; applies only when a parent needs mental health treatment and cannot afford it |
| California | Family Code § 4400; one of the older statutes; rarely enforced but legally valid |
| Connecticut | The only state that caps the parent’s age; the law applies only when the parent is under 65 |
| Delaware | Duty of support extends to children; jurisdiction is assigned to the Family Court |
| Georgia | Requires support when a parent is unable to maintain themselves |
| Indiana | Has more filial legislation on the books than any other state |
| Kentucky | Criminal and civil penalties exist, but enforcement is uncommon |
| Louisiana | Civil obligation to support indigent parents |
| Massachusetts | Criminal penalties are possible, but rarely pursued |
| Mississippi | Statutory duty to support indigent parents |
| Nevada | NRS 428.070; conditional liability only (written agreement, asset control, or sufficient income) |
| New Hampshire | Support is required when a relative’s income exceeds the reasonable subsistence level |
| New Jersey | Statute exists; no reported modern enforcement cases |
| North Carolina | Criminal penalties written into law; infrequently used |
| North Dakota | One of the few states with documented modern enforcement |
| Ohio | Duty of support with the ability to pay as a factor |
| Oregon | Statutory obligation; rarely enforced |
| Pennsylvania | The most actively enforced filial law in the country |
| Rhode Island | Duty of support exists under statute |
| South Dakota | Documented enforcement; courts have issued modern judgments |
| Tennessee | Statutory obligation with financial ability as a condition |
| Utah | Some sources report this law may have been repealed as of 2024; verify locally |
| Vermont | One of the few states with potential jail time for refusal to support an indigent parent |
| Virginia | Requires support from adult children over 18; caps liability at 60 months for institutionalized parents |
| West Virginia | Filial duty exists under state statute |
The remaining 23 states and Washington, D.C., have no filial responsibility statute, meaning adult children in those states face no statutory obligation to cover a parent’s care costs.
Note: This section is for informational purposes only and does not constitute legal advice. State laws change, and individual liability depends on specific facts and circumstances. Consult a qualified attorney before making any decisions.
States that Actively Enforce Filial Responsibility Laws
Not all filial responsibility states enforce their statutes equally. Although nearly 30 states still have these laws, most are dormant and rarely used, largely due to the expansion of Medicaid.
Pennsylvania, North Dakota, and South Dakota are most often linked to active enforcement. Pennsylvania is especially notable because of the 2012 case Health Care and Retirement Corporation of America v. Pittas.
In that case, a son was ordered to pay nearly $93,000 in unpaid nursing home bills after his mother left the facility and moved to Greece. The ruling was significant because he had not signed a care agreement or played any formal role in her admission.
The court found him liable solely under Pennsylvania’s filial responsibility statute, 23 Pa. C.S. § 4603, because he was financially able to pay.
States such as New Jersey, Connecticut, Virginia, and Massachusetts fall into a gray area. Their laws remain in effect, but documented modern enforcement is rare. Even so, they can create potential legal exposure for adult children in certain circumstances.
How Does Filial Responsibility Actually Get Triggered?
Knowing which states have filial responsibility laws is only part of the picture. The bigger question is when these laws can actually apply.
Most cases follow a common pattern: a parent enters a nursing home or care facility, but Medicaid approval is still pending. During this gap, bills can build up.
If the parent has no funds available and coverage has not yet begun, the facility may attempt to recover payment from the parent’s adult children.
In active enforcement states, courts have held that providers do not always have to wait for Medicaid approval before seeking payment.
Other common triggers include:
- No Medicaid Qualification: A parent may have too much income or too many assets to qualify for Medicaid yet still be unable to afford the full cost of care.
- Signed Responsibility Agreements: Some facilities ask relatives to sign as a “responsible party.” In some states, that signature can create liability even if the filial statute alone would not.
- Asset Transfers: If a parent transfers assets during Medicaid’s five-year look-back period, coverage may be delayed or denied, resulting in unpaid bills.
The Legal Information Institute explains that related legal doctrines, such as the doctrine of necessaries, can vary significantly by jurisdiction. The same is true for filial responsibility laws, which is why state-specific guidance is so important.
How to Protect Yourself if You Live in a Filial Law State
The best way to reduce exposure under filial responsibility laws is through proactive planning. The strategies below address the most common situations that lead to liability.
1. Start Medicaid Planning Early
Medicaid’s five-year look-back period can create eligibility delays if assets are transferred too close to the date of a care application.
Planning before a parent needs long-term care is typically far more effective than trying to solve problems after a nursing home admission.
In some cases, learning how to set up a family trust correctly can be part of a broader Medicaid planning strategy and help protect assets while maintaining eligibility goals.
2. Review Care Facility Agreements Carefully
Before signing any admission paperwork, read it carefully and make sure you understand every obligation it creates. Documents that label you as a “responsible party” or “financial guarantor” may expose you to personal liability for a parent’s care costs.
In many situations, contractual obligations pose a greater legal risk than the filial statute itself. If anything is unclear, consider having an attorney review the agreement before you sign.
3. Be Cautious with Asset Transfers
Transferring money or property without understanding Medicaid rules can backfire. Improper transfers may delay benefits, trigger penalty periods, and leave significant care costs unpaid.
These issues can increase the family’s financial exposure and make it more difficult for a parent to qualify for Medicaid when care is needed most.
4. Consider Long-Term Care Insurance
Long-term care insurance can help cover future care expenses and reduce the likelihood that costs will fall on adult children. It can also provide greater flexibility in choosing care options, including in-home care, assisted living, or nursing facilities.
However, coverage is generally most affordable and accessible when purchased before significant health issues arise. Starting the conversation early can help families secure better coverage and avoid limited eligibility later in life.
5. Consult an Elder Law Attorney
Filial responsibility laws vary significantly by state. An elder law attorney can evaluate your family’s situation, explain any potential liability, and recommend strategies tailored to your state’s laws.
They can also help you navigate Medicaid planning, review care agreements, and identify legal protections that may reduce your financial risk.
6. If You Receive a Payment Demand
Do not assume a demand for payment is automatically valid. In many cases, a care facility must prove that you have the financial ability to contribute after meeting your own reasonable living and family obligations
Financial hardship may be a valid defense depending on the laws in your state.
Note: This section is for informational purposes only and does not constitute legal advice. Consult a qualified attorney to evaluate your specific situation.
When Should You Talk to a Lawyer?
You do not need to wait until a bill, collection notice, or lawsuit arrives.
If your parent lives in a state with a filial responsibility law or is considering long-term care, a conversation with an experienced elder law attorney can help you understand your potential exposure before problems arise.
Situations that may warrant legal guidance include:
- A parent is entering a nursing home or assisted living facility, and Medicaid has not yet been approved
- A facility is asking you to sign admission paperwork as a co-signer or responsible party
- You have received a collection notice or lawsuit from a care facility on your parent’s behalf
- Your parent recently transferred assets, and you are concerned about Medicaid look-back implications
The goal is to understand your legal and financial position while there is still time to take preventive action. In some cases, related financial issues may also come into play.
For example, understanding personal injury settlement amounts can be important when a parent’s care costs result from an accident or injury caused by another party.
Conclusion
Filial responsibility laws remain on the books in many states, yet most families do not learn about them until a parent’s care costs become a problem.
While enforcement is uncommon, the financial consequences can be significant when these laws are applied.
The key takeaway is that timing matters. Liability concerns often arise during Medicaid coverage gaps, after poorly understood admission agreements are signed, or when asset transfers create eligibility issues.
These situations are far easier to address before a parent requires long-term care than after bills begin to accumulate. If you live in one of the filial law states, understanding how your state’s laws work can help you avoid costly surprises.
Taking time to plan ahead and seek legal guidance when necessary is often the best way to protect both your parent’s care options and your own financial security.
Frequently Asked Questions
Can a Nursing Home Sue Me Directly for My Parent’s Unpaid Bills?
Yes. In states with active filial responsibility laws, a nursing home or care facility may sue an adult child for unpaid care bills. The facility usually must show that you have the financial ability to pay after covering your own household needs.
Does Filial Responsibility Apply if I Live in a Different State than My Parent?
It can. The key issue is often where your parent received care. If that state has a filial responsibility law, a facility may try to bring a claim there, even if you live elsewhere. An attorney in your parents’ state can help assess the risk.
What Defenses Are Available if I Am Sued Under a Filial Responsibility Law?
Common defenses include financial inability to pay, childhood abandonment, abuse, or neglect by the parent. Courts may also consider your own family and household obligations before deciding whether you owe anything.
Does Qualifying My Parent for Medicaid Eliminate Filial Responsibility Risk?
Medicaid greatly reduces the risk because it pays for covered care directly. The main concern is the gap before Medicaid approval, during which unpaid bills can accumulate. Early Medicaid planning is the best way to reduce that exposure.