You’ve probably heard people use “will” and “trust” like they mean the same thing.
Maybe a friend mentioned setting one up, or you saw an ad promising to help you “avoid probate,” and weren’t sure what that meant for your situation.
The will vs trust confusion is common, and it’s worth clearing up before you commit to either one.
Estate planning attorneys see this mix-up often, usually after someone has signed paperwork that does not do what they assumed it would.
The right setup depends on your family, what you own, and how you want things handled while you’re still around.
Start with what each document actually does, then see how it holds up in your situation.
What are a Will and a Trust?
A will and a trust both decide what happens to your stuff. The big difference is timing.
A will only kicks in after you die. It names who gets what, and it names guardians for your kids. Getting there means going through probate, which is a court process.
A trust works differently. It’s a legal setup that can manage your assets while you’re alive and hand them off after you die. Assets in a trust can skip probate entirely.
Here’s the catch. A trust only protects what’s actually inside it.
If you sign the trust paperwork but never move your house or accounts into it, that property isn’t covered. It still goes through probate like it would with a will.
Types of Trusts
Not all trusts work the same way. The one you choose affects how much control you keep and what protection it offers.
Revocable Trust
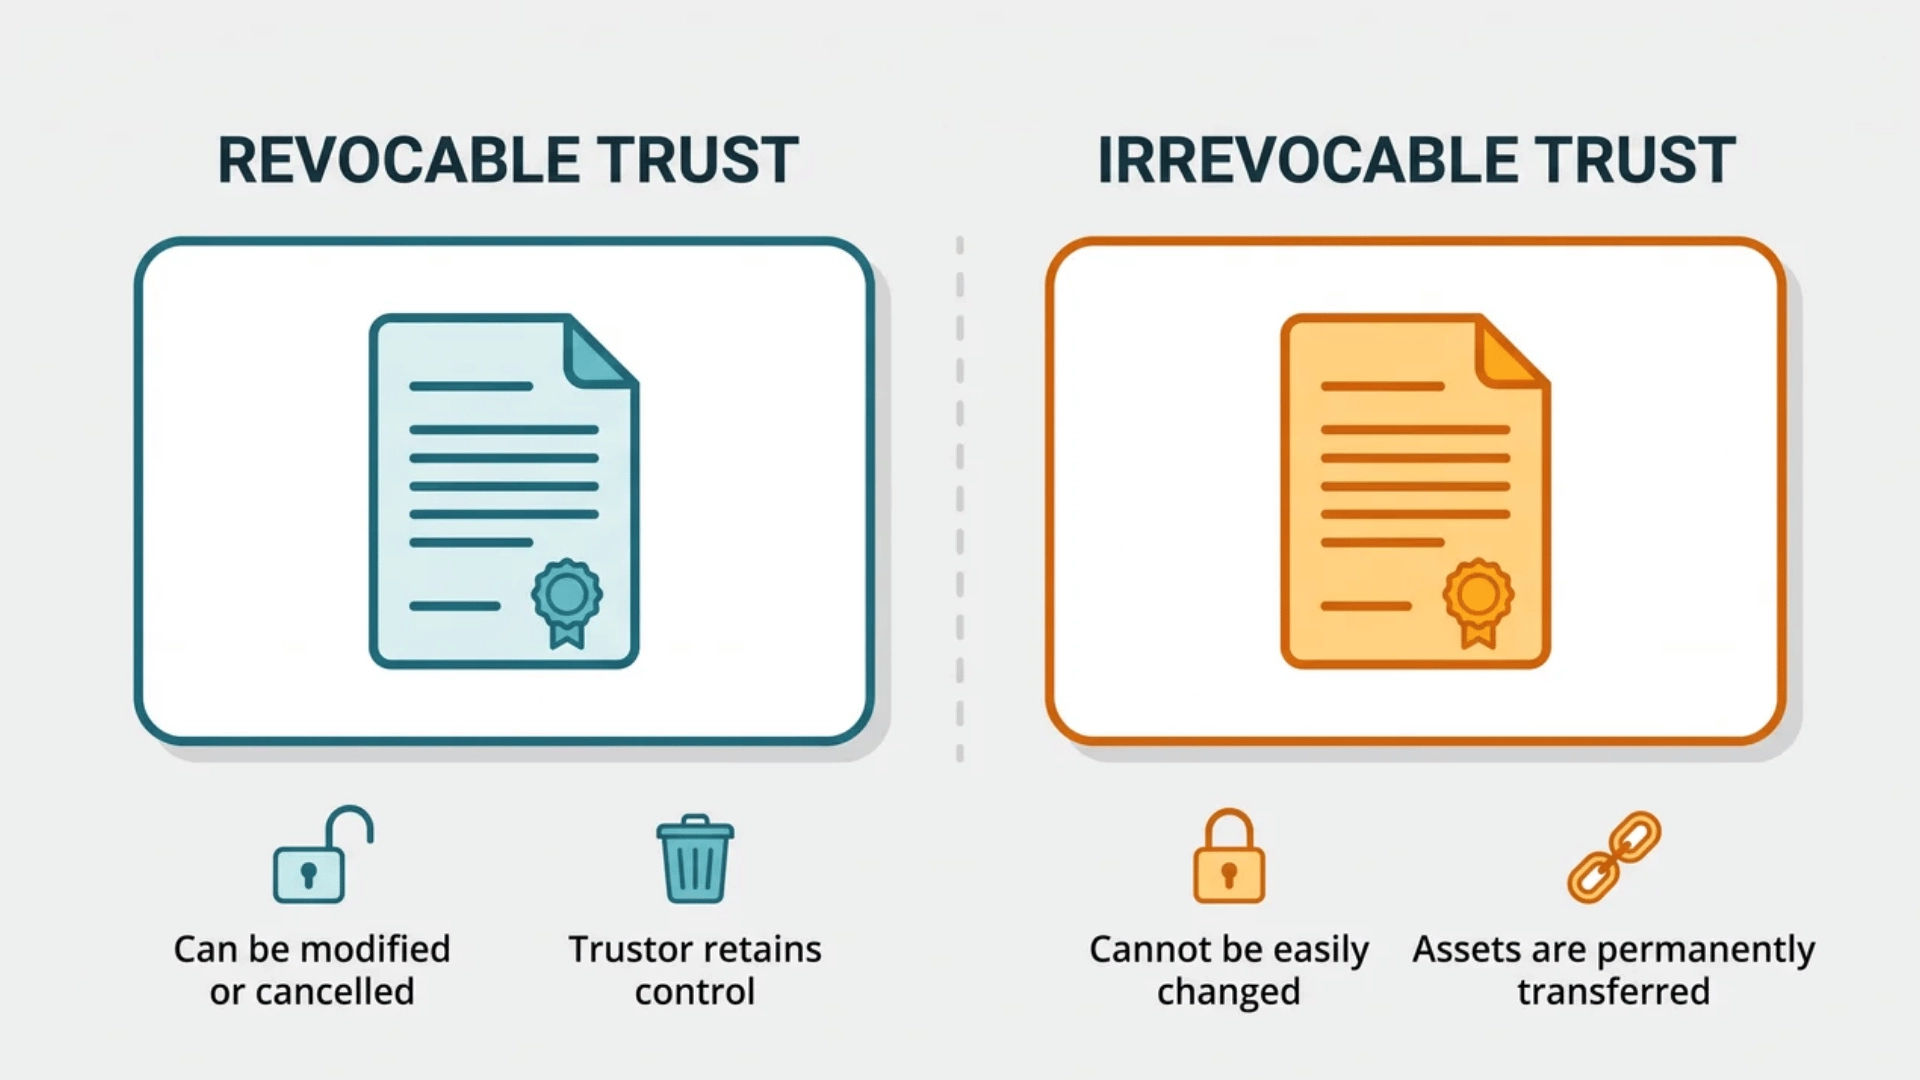
Most people default to a revocable living trust, and for good reason. It lets you change the terms, add assets, or cancel it entirely while you’re alive.
For most people, starting with a revocable trust makes sense, since ownership of the property in a revocable trust stays flexible without locking you into permanent decisions.
Irrevocable Trust
An irrevocable trust works differently. Once it’s set up, you generally can’t change or undo it.
That trade-off exists for a reason. Irrevocable trusts can protect assets from creditors or help with Medicaid planning in ways a revocable trust can’t.
If asset protection or long-term care planning is part of your situation, it’s worth asking your attorney whether an irrevocable trust is a better fit.
How a Will and a Trust Differ in Practice?
A will and a trust look similar from the outside.
What separates them is how much upkeep each one needs to actually work. Here’s the side-by-side comparison, so you can see where each one stands on its own:
| Aspect | Will | Trust |
|---|---|---|
| Takes effect | After death | As soon as it’s signed and funded |
| Probate | Required | Skipped, but only for funded assets |
| Privacy | Public record | Stays private |
| Guardianship for minors | Yes | No |
| Incapacity coverage | None | Successor trustee can step in |
| Setup | Simple | Requires retitling assets |
| Ongoing upkeep | Minimal | Needs updating as you acquire new assets |
1. Probate and Privacy
A trust is often marketed as a way to skip probate. That part is true, but only for what’s actually inside the trust. Some people sign the trust paperwork and stop there.
They never move the house deed or bank accounts into it. When they die, that property still goes through probate, the same as it would with a will.
If probate does happen, an estate or probate attorney is typically the one who guides the filing through court.
Moving assets into the trust is what makes it work. Signing the document isn’t enough on its own.
2. Guardianship and Incapacity
These are two different problems, and each one needs a different document.
If you have minor children, you need a will. It’s the only document that can name a guardian for them.
A trust handles a different situation: what happens if you’re alive but unable to manage your own affairs. A successor trustee can step in right away. A will doesn’t cover this. It only takes effect after death.
3. Cost and Complexity
A will is usually simpler to set up. You list your beneficiaries, sign it, and you’re mostly done.
A trust takes more work. Beyond drafting the document, you have to retitle assets into the trust’s name, which means updating deeds and account ownership, then keeping that current as you acquire new assets.
Skip that step, and the asset stays out of the trust. It still goes through probate.
The living trust scams page from California’s Attorney General is worth a read if you’re being pitched a trust package, since it lays out the deceptive estate planning sales tactics regulators see most often.
Difference Between Living Trust vs. Living Will
These two terms sound alike, and the overlapping wording trips up a lot of people, but they cover completely different decisions.
One deals with your property, and the other deals with your body.
Mixing them up can leave a real gap in your planning, especially if you assume one document is doing a job it was never meant to do.
Here’s how they compare:
| Aspect | Living Trust | Living Will |
|---|---|---|
| What it is | A legal entity that manages and transfers your assets | A medical directive for end-of-life care decisions |
| Covers | Property, money, and other assets | Health care preferences, not property |
| Takes effect | As soon as it’s signed and funded | Only if you’re unable to communicate medical wishes |
| Who’s involved | A trustee and successor trustee manage the assets | A designated health care agent carries out your wishes |
| Common use | Avoiding probate and managing assets during incapacity | Specifying life support, resuscitation, and treatment preferences |
A living trust holds no authority over your medical care, no matter how it’s worded.
If you’re incapacitated and haven’t signed a separate living will or health care directive, doctors and family members may have to guess at your wishes or rely on state default rules.
The reverse is also true. A living will has no power over your house, bank accounts, or other property.
It only speaks to end-of-life medical decisions, and it stays inactive until a doctor determines you can’t communicate your wishes yourself.
A quick way to check: if you’re talking about medical care, you mean a living will. If you’re talking about property, you mean a trust.
Most complete estate plans include both, along with a will, since each one covers a piece of planning the others don’t.
Which One is Right for You?
You don’t have to guess at this. A few details about your situation usually make the answer clear.
| Situation | Trust | Will | Which Suits Better? |
|---|---|---|---|
| You own real estate in more than one state. | A trust can hold properties in different states and help avoid separate probate proceedings. | A will may require probate in each state where you own property. | Trust |
| You have minor children. | A trust can manage assets for your children but cannot name their guardian. | Only a will can name a legal guardian for minor children. | Will, even if you also have a trust |
| Your estate is small and simple. | The setup cost and ongoing upkeep may not provide enough benefit. | A will is usually simpler and more affordable for uncomplicated estates. | Will |
| Privacy matters to you. | Trust assets generally remain private and avoid public probate records. | A will usually becomes public after it enters probate. | Trust |
None of these rule out the others. You might have minor kids and still benefit from a trust for the real estate you own.
The goal is matching the tool to what’s actually true about your situation, rather than choosing one over the other by default.
A trust doesn’t usually replace a will, and most complete estate plans use both, since a trust only covers what’s inside it.
A pour-over will catches anything left outside the trust, so nothing slips through by accident.
Signing a trust document isn’t the same as funding it. If you never move assets into the trust, it offers no more protection than a will alone.
How Do You Create a Trust?
Setting up a trust involves more moving parts than a will, since it must be funded correctly to work. Here’s what the process generally involves:
Step 1. Decide what type of trust fits your situation.
Most people start with a revocable living trust, since it offers flexibility while you’re alive. An irrevocable trust suits situations involving asset protection or long-term care planning instead.
Step 2. Choose a trustee to manage the trust, along with a successor trustee.
The trustee handles the trust setup while you’re able to manage it yourself, and the successor trustee steps in if you become incapacitated or after you die, so pick people you trust to follow your instructions.
Step 3. Draft the trust document, listing your beneficiaries and the terms of the trust.
Spell out who receives what, when they receive it, and any conditions attached, so the trustee has clear direction to follow later.
Step 4. Sign the trust in front of a notary, based on you state’s requirements.
Notarization rules vary by state, so check what your state requires before finalizing the signing.
Step 5. Fund the trust by retitling assets.
Fund the trust by retitling assets like your home, accounts, and other property in the trust’s name.
This is the step people skip most often, and skipping it means the trust isn’t doing what it was set up to do, since only assets retitled into the trust avoid probate.
Once every asset is properly retitled, the trust is fully funded and ready to manage and transfer your property as intended.
How Do You Create a Will?
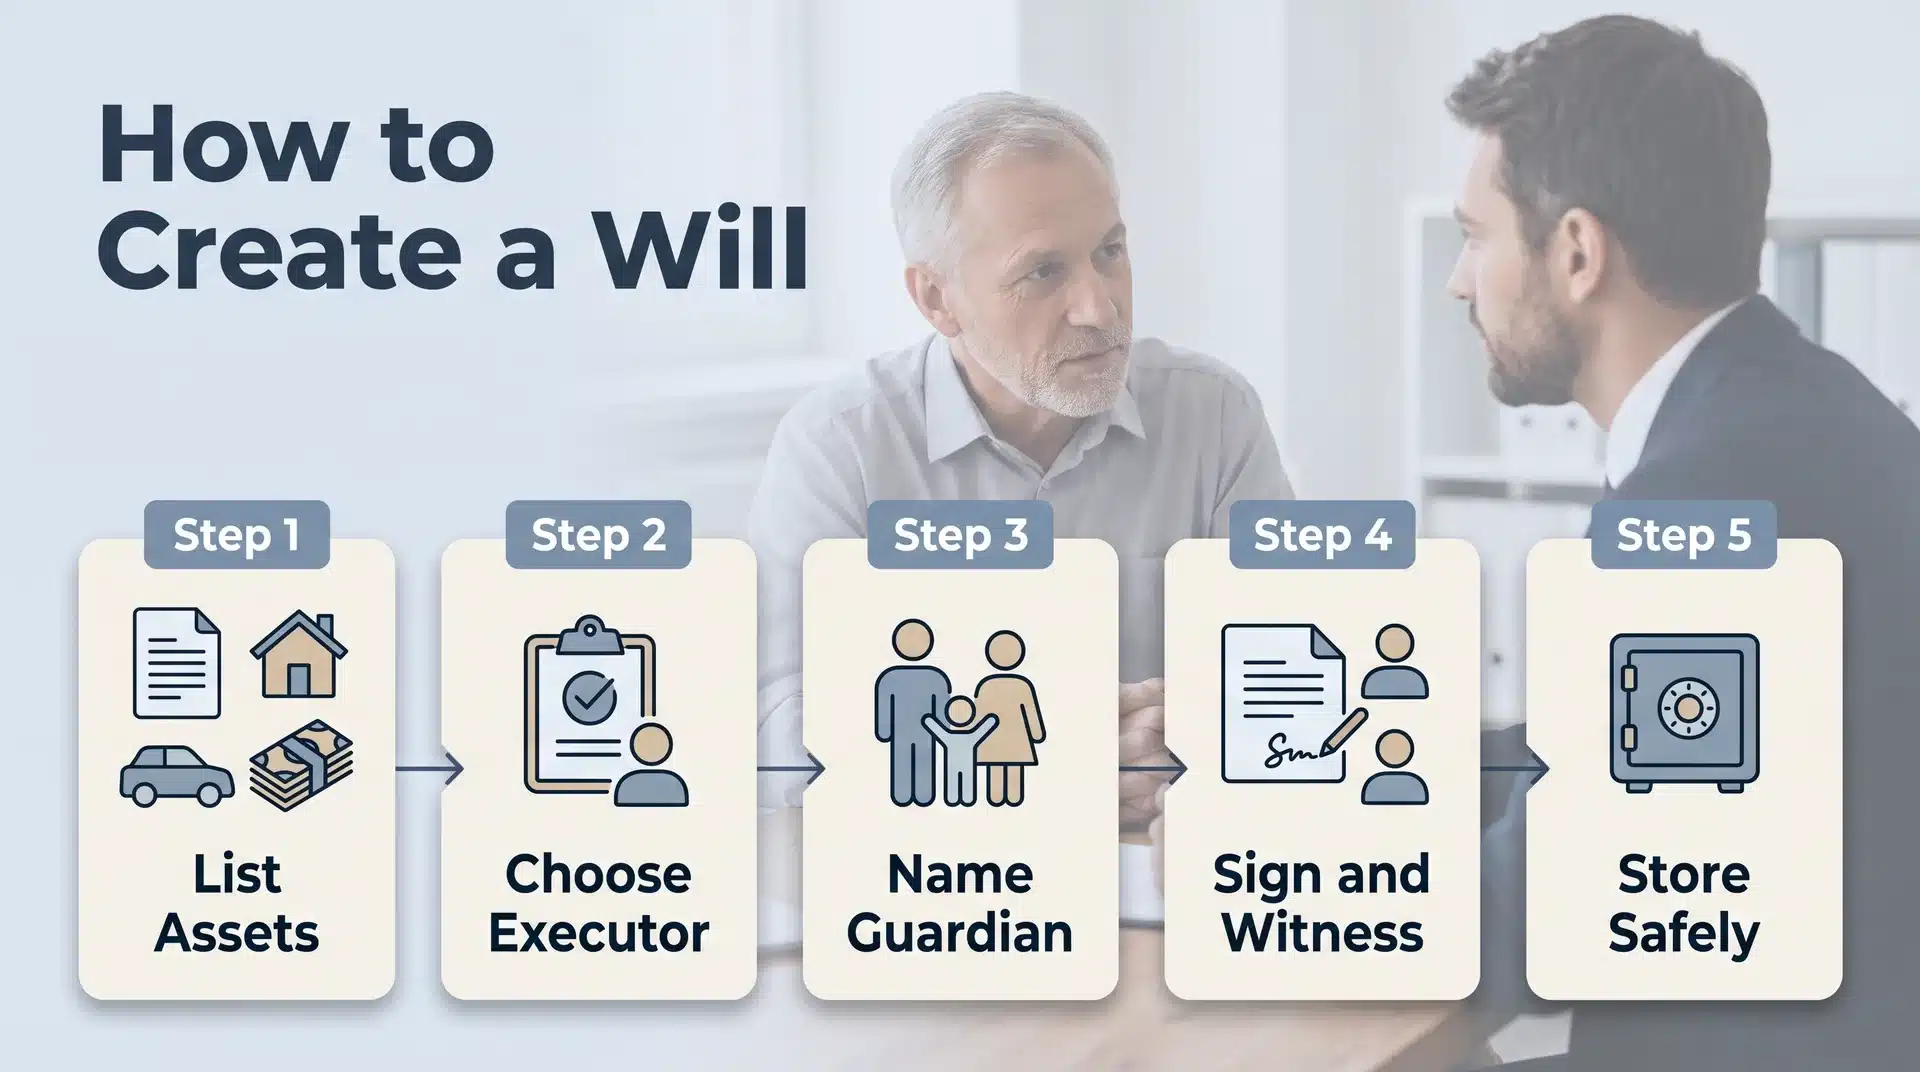
Creating a will is usually more straightforward than setting up a trust. Here’s what the process generally involves:
Step 1. List your assets and decide who should receive them.
Walk through property, savings, investments, vehicles, and personal belongings, then match each item to a specific person to avoid confusion later.
Step 2. Choose an executor to carry out the instructions in your will.
This person files the will with the probate court, settles debts and taxes, and distributes assets, so pick someone organized and willing to take on the role.
Step 3. Name a guardian for any minor children.
This decision determines who raises your kids if something happens to both parents, so talk to the person you have in mind before naming them.
Step 4. Sign the will in front of the required witnesses for your state.
Rules on witness count and eligibility differ by location, so check whether witnesses can be related to you or named as beneficiaries.
Step 5. Store the original somewhere safe.
Store the original somewhere safe, and let your executor know where to find it. A fireproof home safe or attorney’s office both work, but the location shouldn’t be a mystery when it’s actually needed.
Once it’s signed and witnessed correctly, the will is legally valid and ready to guide your estate.
Conclusion
A will and a trust solve different problems in the will vs trust decision. A will names guardians and directs what happens to your things after you’re gone.
A trust can manage your assets while you’re alive, and it can skip probate, but only for what’s moved into it. Which one fits depends on your family, what you own, and the size of your estate.
Many people end up needing both, since a will can catch anything a trust leaves out.
If you’re ready to set one up, decide which type of trust matches your situation, then get the funding step right from day one.
Talk to an estate planning attorney so your plan holds up when it matters most.
Frequently Asked Questions
How Much Should a Will and Trust Cost?
Costs vary based on complexity, location, and whether you hire an attorney or use online services. Trusts typically cost more upfront than wills because they involve extra paperwork, retitling assets, and ongoing maintenance. A simple will often has a modest flat fee, while a fully funded trust usually costs more once you add attorney time and retitling.
Can You Change a Trust After Creating It?
Yes, a revocable living trust can be updated, amended, or revoked at any time while you’re alive and mentally competent. This flexibility lets you adjust beneficiaries, trustees, or terms as your circumstances change over time. An irrevocable trust works differently, since it generally cannot be changed once signed, which is part of why choosing the right type matters from the start.
Do You Need a Lawyer to Create a Trust?
Not always, but an attorney helps ensure it’s properly funded and structured to comply with your state’s laws. Skipping legal guidance raises the risk of errors that could leave assets unprotected or contested later. A trust that is signed but never funded offers no real protection, and an attorney often catches that gap before it becomes a problem.
What Happens If You Die Without a Will or Trust?
State intestacy law decides who inherits your assets, following a fixed order of relatives that may not match what you would have chosen. This can take longer and cost more than a planned distribution. Minor children may end up with a court-appointed guardian instead of one you chose, which is one reason a will matters even alongside a trust.